
In the high-stakes 2026 coastal real estate market, a single miscalculation in your initial offer can cost you more than the price of a luxury vehicle. You likely feel the pressure of Manhattan Beach's competitive landscape or the complexity of Redondo's specific zoning laws. It's easy to feel overwhelmed by the speed of transactions and the fear of making common first time home buyer mistakes South Bay residents often regret. Most buyers enter this process with a sense of trepidation; they worry about overpaying in a high-demand environment or failing to account for the true cost of coastal maintenance and insurance. These concerns are valid in an area where local nuances dictate your long-term financial health.
This guide provides a methodical, data-driven checklist to help you navigate these challenges with the precision of a scholar. As an expert guide, I believe in replacing anxiety with rigorous analysis and a structured plan of action. We'll examine state and county assistance programs that actually work for high-cost areas like El Segundo and the Beach Cities. You'll gain a clear, risk-mitigating roadmap to purchase that builds genuine confidence in your neighborhood selection. This disciplined approach ensures you find a perfect fit within our community. Robert Neff, Ph.D., Realtor® DRE #02442812.
Key Takeaways
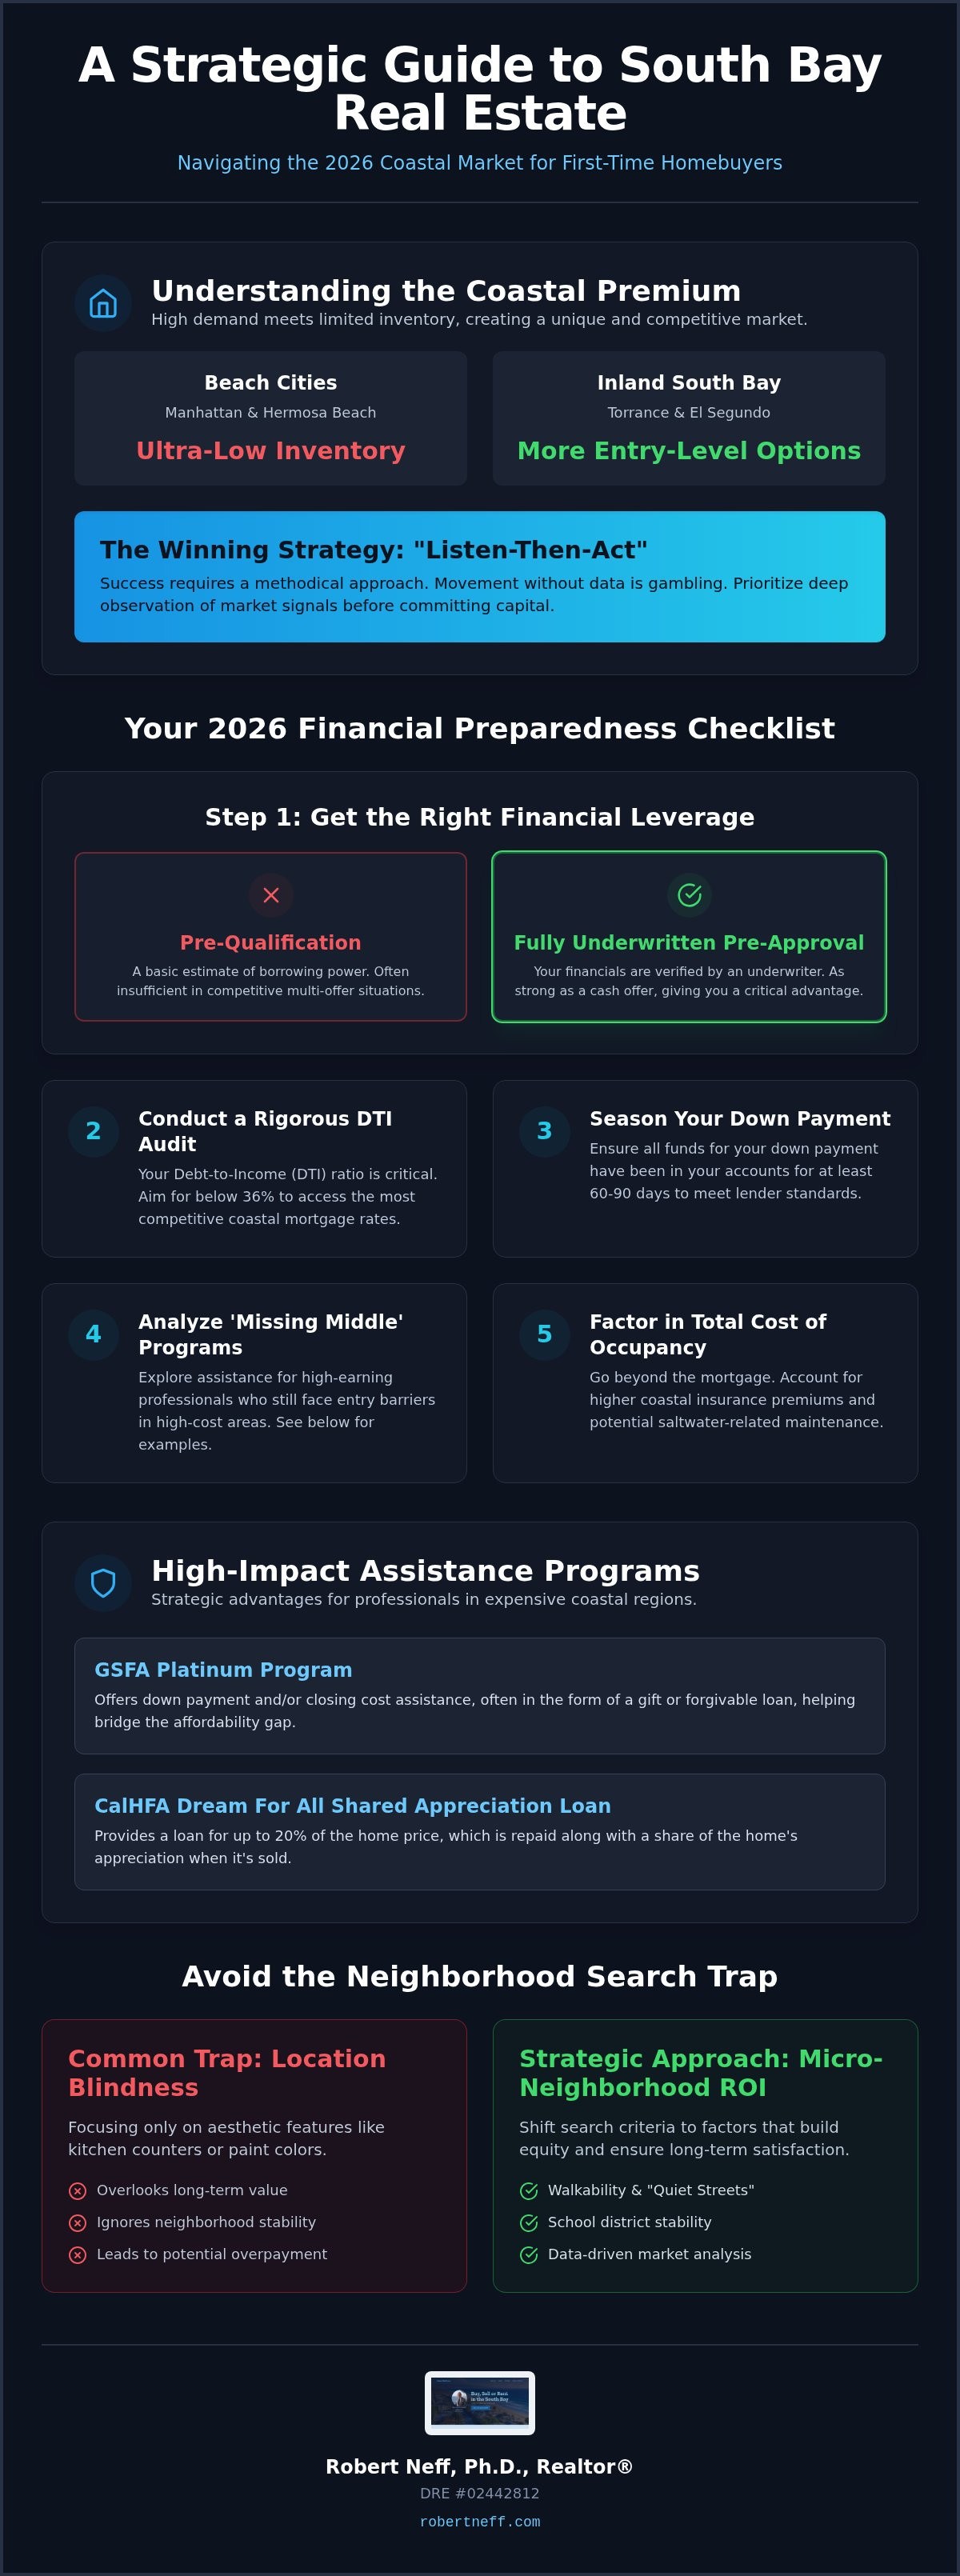
- Identify the 2026 South Bay Coastal Premium and learn why a methodical, "listen-then-act" strategy is the foundation for success in a high-demand market.
- Avoid common first time home buyer mistakes South Bay applicants make by prioritizing a fully underwritten pre-approval over a simple pre-qualification letter.
- Explore high-impact assistance programs like the GSFA Platinum and CalHFA Dream For All, which offer strategic advantages for professionals in expensive coastal regions.
- Shift your search criteria from aesthetic home features to micro-neighborhood ROI, focusing on critical factors like walkability and school district stability.
- Utilize academic rigor and data-driven market analysis from Robert Neff, Ph.D., DRE #02442812, to navigate high-stakes negotiations with professional grace.
Navigating the South Bay Coastal Premium: A Framework for First-Time Success
The South Bay Coastal Premium is a specific economic phenomenon where high demand meets a fixed, limited inventory of land. In 2026, this premium is more pronounced than ever. One of the most common first time home buyer mistakes South Bay newcomers commit is treating this region like a standard suburban market. You cannot approach a home in Hermosa Beach with the same negotiation tactics used in a sprawling inland development. The inventory simply doesn't support it. Success requires a "listen-then-act" framework. This methodical approach prioritizes deep observation of market signals before committing capital. In a high-stakes environment, movement without data is just gambling.
The Beach Cities vs. The Inland South Bay
Inventory trends for 2026 show a widening gap between the Beach Cities and more accessible areas like Torrance. While Manhattan Beach remains a stronghold of ultra-low inventory, Torrance often provides more entry-level options for those willing to trade proximity to the sand for more square footage. Conversely, Redondo Beach offers variety in the townhome market, providing a unique middle ground for first-time buyers. The financial landscape is equally nuanced. Understanding the cost of living El Segundo CA offers is vital for accurate mortgage qualification. For instance, El Segundo's "Quiet Streets" are highly sought after. Buying into these specific micro-neighborhoods acts as a strategic hedge. These areas tend to appreciate faster and offer more stability for your first major equity investment.
The Expert Guide Persona in Real Estate
An academic approach to real estate transforms the experience from a stressful transaction into a disciplined investment. Using a PhD-led methodology means every recommendation is backed by rigorous market analysis. This reduces the natural anxiety that comes with a first-time purchase. We look at the data to determine if a home's price reflects its true value or if it is inflated by temporary market heat. Professional staging and pricing analysis are often viewed as seller tools, but they are equally valuable for buyers. I use these models to deconstruct a listing. We identify if a property is priced for a quick sale or if the seller is testing the 2026 market limits. This level of scrutiny leads to more disciplined negotiation outcomes, ensuring you don't overpay for the coastal lifestyle. Robert Neff, Realtor® DRE #02442812.
Strategic Financial Errors: A 2026 First-Time Buyer Checklist
Securing a home in the South Bay requires more than a high credit score; it demands a surgical approach to your financial profile. In the 2026 market, one of the most common first time home buyer mistakes South Bay residents make is failing to present a "clean" financial narrative to lenders. Coastal lenders now prioritize stability and liquidity over simple income figures. To avoid rejection in the eleventh hour, follow this methodical checklist before you begin your search.
- Conduct a rigorous DTI audit: Your debt-to-income ratio should ideally sit below 36% for the most competitive coastal rates.
- Secure a fully underwritten pre-approval: Move beyond basic letters and obtain a mortgage pre-approval in the South Bay that has already cleared the underwriter's desk.
- Analyze 'Missing Middle' programs: Research assistance programs specifically designed for high-earning professionals who still face entry barriers in high-cost counties.
- Season your down payment: Ensure all funds have remained in your accounts for at least 60 to 90 days to satisfy 2026 anti-money laundering standards.
- Factor in Total Cost of Occupancy: Coastal living involves higher insurance premiums and saltwater-related maintenance costs that inland models often ignore.
The Underwriting Advantage
In competitive markets like Manhattan Beach, a standard pre-approval letter is often insufficient. Sellers frequently receive multiple offers, including several all-cash bids. To compete, you must achieve "Fully Underwritten" status. This means a lender has already verified your tax returns, professional loans, and student debt. It transforms your offer from a "maybe" into a near-certainty. For South Bay professionals with complex compensation packages or significant medical school debt, this early verification is a non-negotiable step in reducing transaction risk. If you are unsure where to start with this level of preparation, you can consult with a specialized advisor to review your readiness.
Optimizing Your Financial Profile
Achieving a "Coastal-Ready" credit score of 740 or higher is your primary objective. This tier unlocks the most favorable terms for high-value loans common in the Beach Cities. Once you enter the escrow period, your financial behavior must remain static. A common error is making a large purchase, such as a new vehicle or expensive furniture, which can pivot your DTI ratio and disqualify your loan days before closing. Maintain high liquid reserves as well. South Bay transactions often require significant "earnest money" deposits and proof of funds that go beyond the down payment. Robert Neff, Realtor® DRE #02442812.
Assistance Programs for the 'Missing Middle' in the South Bay
One of the most common first time home buyer mistakes South Bay applicants fall into is the "income trap." Many professionals assume their salary disqualifies them from financial support. In 2026, specialized programs target the "missing middle"-high-earning individuals who still struggle with the significant entry costs of the Beach Cities. These aren't just for low-income earners; they're strategic tools for engineers, educators, and healthcare workers looking to anchor themselves in the community. Misunderstanding these options often leads to leaving thousands of dollars in subsidies on the table.
State-Level Strategic Tools
The 2026 status of the CalHFA Dream For All Shared Appreciation Loan remains a focal point for coastal buyers. This model provides a significant down payment in exchange for a share of the home's future appreciation. In rapidly appreciating zones like Hermosa Beach, this is a calculated trade-off. You gain immediate entry into a high-equity market while reducing your monthly debt service. Conversely, the GSFA Platinum program has become the "secret weapon" for South Bay professionals. It features higher income limits than traditional state programs, making it accessible even for those with six-figure salaries. This program provides down payment gifts or soft seconds that don't always require shared equity, offering a cleaner path to full ownership. Robert Neff, Realtor® DRE #02442812.
Local Incentives and Tax Credits
Maximizing your purchasing power involves stacking multiple incentives. Mortgage Credit Certificates (MCC) are a primary example. An MCC allows you to convert a portion of your annual mortgage interest into a direct federal tax credit. This effectively increases your qualifying income in the eyes of lenders. While the L.A. County Home Ownership Program (HOP) is often more restrictive, it's worth evaluating for specific South Bay pockets where property values align with county caps. Other methodical options include:
- Southern California Home Financing Authority (SCHFA): Provides grants for down payments and closing costs for those buying in Los Angeles County.
- WISH and IDEA Grants: These matching programs provide up to a 4-to-1 match on your saved down payment funds, though they require specific seasoning of assets.
- El Segundo Density Bonuses: New residential developments in El Segundo often utilize density bonus laws to include units with specific price protections for first-time buyers.
Identifying these programs requires a "listen-then-act" approach. We first analyze your specific professional profile and then map it against the 2026 eligibility requirements for these grants. This academic rigor ensures you don't overlook a secret weapon that could make a Beach City home a reality. Avoiding common first time home buyer mistakes South Bay residents make starts with knowing that assistance isn't just a safety net; it's a competitive advantage.
The Neighborhood Search Trap: Avoiding Location Blindness
A property's physical structure is malleable, but its geographic coordinates are fixed. One of the most common first time home buyer mistakes South Bay residents commit is prioritizing cosmetic finishes over micro-neighborhood ROI. In 2026, the value of a home is increasingly tied to hyper-local metrics that a casual online search often misses. You might find a renovated interior in Torrance, but if you overlook the school district boundaries or proximity to industrial zones, your long-term equity growth may stagnate compared to a similar home in Palos Verdes. Location blindness isn't just about the view; it's about the data underlying the dirt.
Micro-Market Nuances
School ratings remain a primary driver of resale value, yet their impact varies significantly by city. In Palos Verdes, the academic reputation creates a consistent floor for property values. In contrast, Torrance offers a more varied landscape where specific blocks command premiums based on their "Walk Score." In Hermosa Beach, I advise clients to analyze the "Quiet Score." This metric balances the desire for beach proximity with the need for residential tranquility. El Segundo presents a different strategic opportunity. Its proximity to expanding tech and aerospace hubs ensures a consistent influx of high-earning residents. Redondo Beach remains a prime area for finding "hidden gems." These properties offer oceanfront access at a lower premium than Manhattan Beach's sand section.
Hidden Ownership Costs in the South Bay
Location blindness also extends to the financial obligations tied to specific parcels of land. Newer developments often carry Mello-Roos assessments. These are special taxes used to fund local infrastructure, and they can significantly increase your monthly carrying costs beyond the base mortgage. Coastal properties also face unique insurance requirements. Between saltwater corrosion and updated 2026 flood zone maps, your premiums might be significantly higher than those just a few miles inland. If you're considering a luxury condo, the HOA fees must be scrutinized with academic rigor. These are not static; they cover everything from earthquake insurance to specialized maintenance, and they directly impact your debt-to-income ratio. Identifying these common first time home buyer mistakes South Bay buyers often miss is essential for a risk-mitigated purchase.
I help my clients peel back these layers of complexity to ensure their first home is a sound investment. To begin a methodical analysis of your target neighborhoods, schedule a strategic consultation today. Robert Neff, Realtor® DRE #02442812.
Partnering with a South Bay Coastal Specialist
The complexity of the 2026 market demands more than a traditional real estate agent; it requires a strategic partner who operates with the precision of a scholar. Navigating the competitive landscape of the Beach Cities is a high-stakes endeavor where minor oversights can lead to significant financial setbacks. By partnering with a specialist who understands the data underlying the market, you effectively insulate yourself from the most common first time home buyer mistakes South Bay residents face. My "listen-then-act" methodology ensures that every move we make is deliberate, transparent, and grounded in your specific long-term goals.
The Robert Neff Academic Advantage
My background as a Ph.D. allows me to apply rigorous, data-driven pricing models to every transaction. This academic rigor is your primary defense against the "emotional premium" trap, where buyers overpay due to market heat or aesthetic distractions. We analyze historical trends and 2026 inventory forecasts to ensure your offer is competitive yet disciplined. Throughout the escrow process, I maintain a sequential communication framework. This highly organized approach keeps you informed at every stage, reducing the stress of complex transitions. You aren't just buying a property; you're executing a well-defined strategy with a local resident who values the community's unique lifestyle. Robert Neff, Realtor® DRE #02442812.
Ready to Begin Your Journey?
The path to coastal ownership begins with a professional consultation designed to audit your readiness and define your search parameters. As part of the Kaminsky Real Estate Group at eXp Realty, I provide my clients with access to an extensive network that often includes off-market opportunities. These "quiet" listings are essential in a market where inventory remains the primary hurdle. We will utilize professional market analysis to identify properties that meet our strict criteria for ROI and community fit. To avoid common first time home buyer mistakes South Bay newcomers often regret, you must start with a steady hand and a clear roadmap.
- Strategic Readiness: Review your underwritten status and assistance program eligibility.
- Market Immersion: Analyze micro-neighborhood data in El Segundo, Manhattan Beach, and beyond.
- Network Access: Leverage the Kaminsky Group's deep roots for early listing alerts.
- Disciplined Negotiation: Execute offers based on objective value models rather than market speculation.
Your transition into the South Bay community should be as seamless as it is successful. I am dedicated to providing the intellectual rigor and local expertise required to make that happen. When you are ready to move from observation to action, I am here to guide the way. Schedule your strategic South Bay buyer consultation with Robert Neff today.
Securing Your Future in the South Bay Coastal Market
Success in the 2026 real estate landscape is the result of disciplined research and hyper-local expertise. By prioritizing a fully underwritten pre-approval and leveraging "missing middle" assistance programs, you position yourself as a serious contender against all-cash offers. We have explored how a methodical analysis of micro-neighborhood ROI and hidden coastal maintenance costs protects your long-term equity. Avoiding the common first time home buyer mistakes South Bay newcomers often face requires a transition from emotional browsing to rigorous, data-driven decision making. This structured approach replaces uncertainty with a quiet confidence.
Robert Neff, Ph.D. (DRE #02442812), provides the academic expertise in market analysis and deep local roots in Manhattan, Hermosa, and Redondo Beach needed to navigate this transition with professional grace. Every step of your journey is managed with transparency and a genuine commitment to finding your perfect fit within the community. When you are ready to move forward with a steady hand and a clear strategy, I am here to guide you. Begin your strategic South Bay home search with Robert Neff, Ph.D. today. Your coastal lifestyle is within reach.
Frequently Asked Questions
What is the minimum down payment for a first-time buyer in the South Bay in 2026?
In 2026, the minimum down payment for a first-time buyer in the South Bay typically starts at 3% for conventional loans or 3.5% for FHA-backed mortgages. However, because many coastal properties exceed conforming loan limits, you may encounter jumbo loan requirements of 10% to 20%. Strategic buyers often utilize assistance programs to bridge this gap. It's essential to analyze your specific loan product against the high-value inventory in Manhattan or Redondo Beach to determine your actual cash requirement.
Do I qualify for CalHFA programs if I have a high professional income?
You may still qualify for CalHFA programs even with a high professional income. For 2026, the income limits for Los Angeles County are adjusted to reflect the higher cost of living in coastal regions. Programs like "Dream For All" target the "Missing Middle," allowing individuals earning six-figure salaries to access shared appreciation loans. We must verify your specific household income against the latest 2026 CalHFA limits to ensure you don't overlook these strategic financial tools.
How does the GSFA Platinum program help 'Missing Middle' buyers in high-cost areas?
The GSFA Platinum program serves as a powerful tool for South Bay professionals by offering higher income limits than many traditional state-run programs. It provides down payment and closing cost assistance in the form of a gift or a soft second mortgage. This is particularly effective in high-cost areas where saving a full 20% down payment is a significant hurdle. It allows you to preserve liquidity while securing a home in competitive Beach City neighborhoods.
What are Mello-Roos, and are they common in El Segundo or Manhattan Beach?
Mello-Roos assessments are special taxes used to fund local infrastructure, and while they are less common in established parts of Manhattan Beach, they frequently appear in newer developments. In El Segundo, you may find these assessments in specific residential pockets or recently revitalized industrial-to-residential conversions. Identifying these costs early is vital, as they significantly impact your monthly carrying costs. One of the common first time home buyer mistakes South Bay applicants make is failing to factor these taxes into their total debt-to-income ratio.
How long does the first-time buyer process typically take in the South Bay coastal market?
The first-time buyer process in the South Bay coastal market typically spans three to six months from the initial consultation to closing. This timeline includes a methodical search phase, obtaining a fully underwritten pre-approval, and navigating a competitive offer environment. Once an offer is accepted, the escrow period generally lasts 30 days. However, the speed of the 2026 market means you must be prepared to act decisively once the right property is identified through our data-driven search process.
Can I use multiple down payment assistance programs together (stacking)?
You can often use multiple down payment assistance programs together, a strategy known as stacking. For example, a buyer might combine a Mortgage Credit Certificate (MCC) to reduce federal tax liability with a GSFA Platinum grant for down payment support. This approach requires careful coordination between your Realtor® and a knowledgeable lender to ensure all program requirements are met. Stacking maximizes your purchasing power and reduces the long-term cost of coastal ownership in high-demand areas.
What credit score is required for the best 2026 mortgage rates in California?
To secure the most favorable 2026 mortgage rates in California, a credit score of 740 or higher is generally required. While you can qualify with lower scores, this "Coastal-Ready" tier unlocks the lowest interest rates and reduced private mortgage insurance premiums. Maintaining this score is a critical component of our risk-mitigating roadmap. We recommend a methodical review of your credit report at least six months before you intend to enter the competitive South Bay market.
How do I identify the quietest streets in El Segundo for a family home?
Identifying the quietest streets in El Segundo requires a "walk the ground" approach combined with local resident expertise. We typically look at residential pockets on the east side of town, away from the primary transit corridors of Imperial Highway and Pacific Coast Highway. Streets with limited through-traffic and proximity to local parks often provide the tranquility families desire. Avoiding common first time home buyer mistakes South Bay residents encounter often involves this level of hyper-local analysis to ensure long-term lifestyle satisfaction.


