
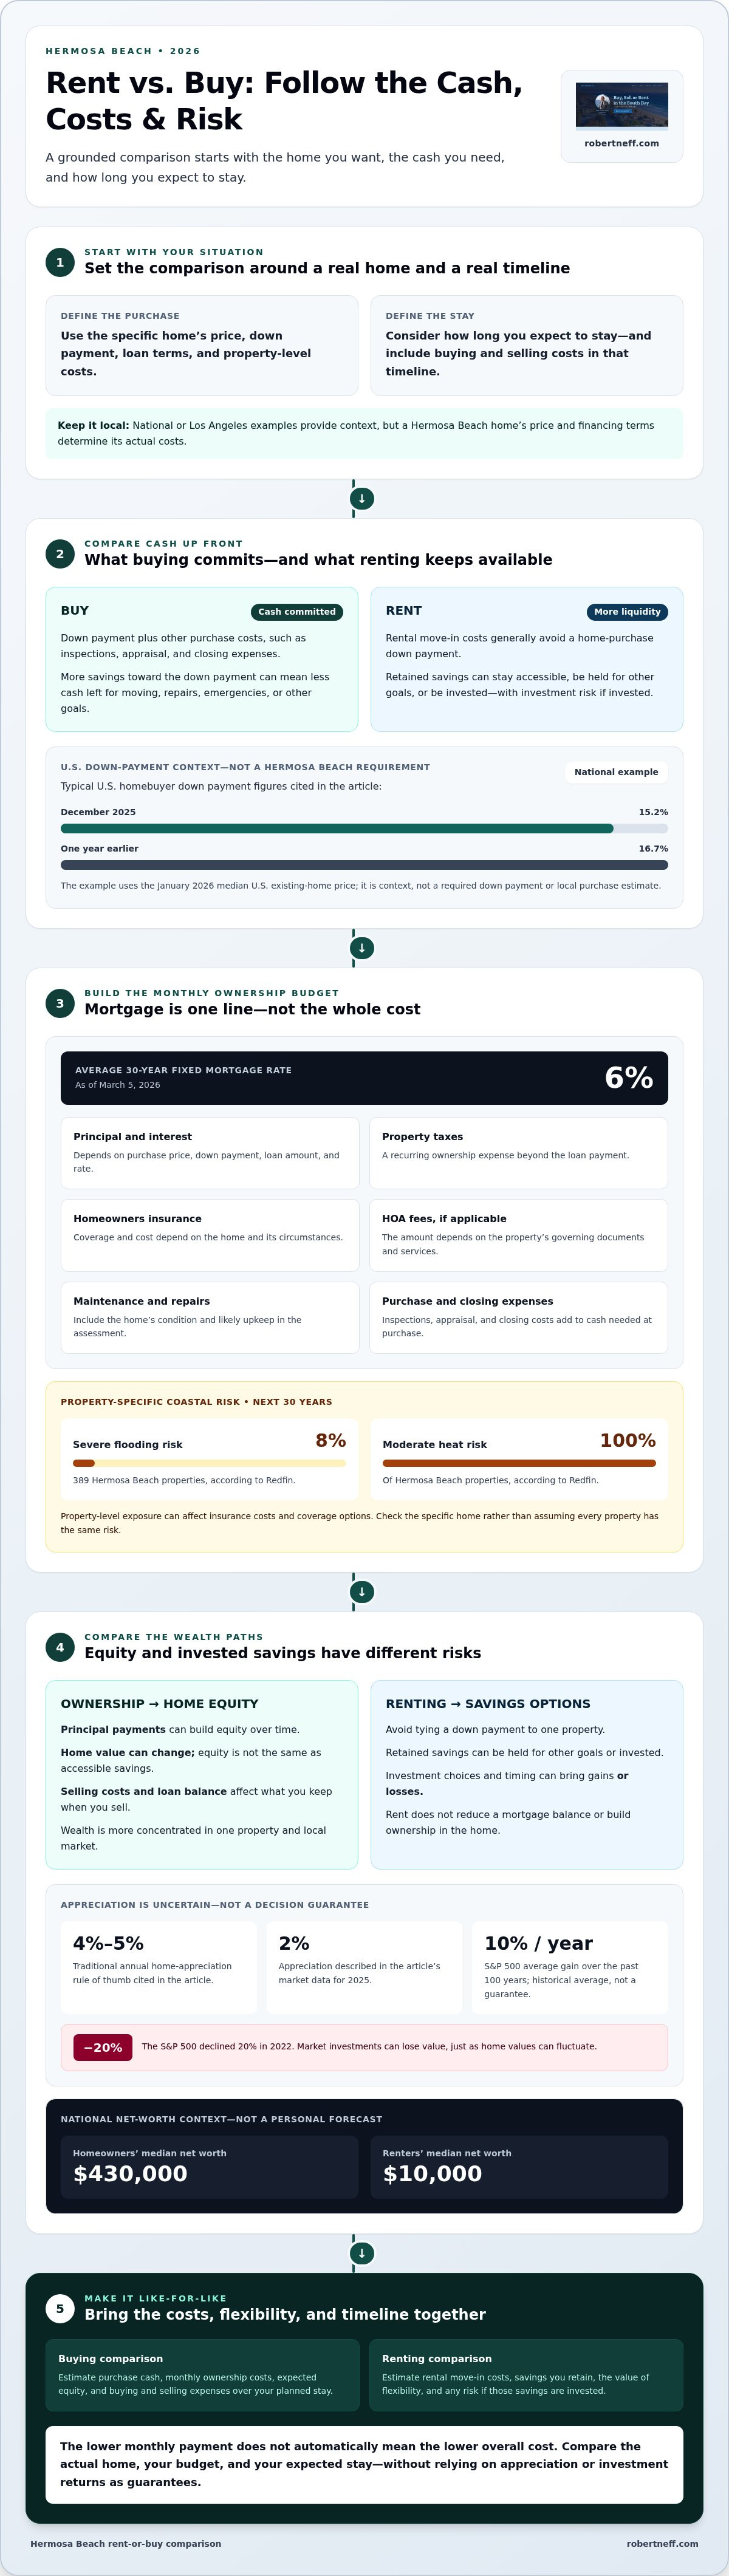
The lower monthly payment doesn't always mean the lower overall cost. The answer to renting vs. buying in Hermosa Beach in 2026 depends on how long you expect to stay and whether ownership costs are outweighed by the equity you build.
It’s easy to see buying as the natural path to putting down roots, while renting can feel like money spent without a lasting return. Yet renting may preserve savings and make moving easier. Buying can build equity over time, but also brings added costs and exposure to changes in the housing market.
This guide compares upfront expenses, monthly costs, savings, flexibility, and the effect of your expected stay. You’ll see which tradeoffs matter most, why national or metro-level comparisons may not reflect a specific Hermosa Beach home, and how to use your timeline and budget to make a grounded decision.
Key Takeaways
- Compare the full cash needed to buy, including the down payment and closing costs, with the savings you’d retain by renting.
- Budget for ownership expenses beyond the mortgage, such as property taxes, insurance, maintenance, and any HOA fees.
- Weigh the potential to build home equity against the flexibility of renting and the risks of investing your savings elsewhere.
- Your expected stay matters: account for buying and selling costs alongside the time available to build equity.
- Use your budget, desired home, and likely timeline together to decide which option better fits your plans in Hermosa Beach.
Down payments and investment volatility
Buying in Hermosa Beach requires a substantial upfront commitment, and the down payment is only one part. A percentage-based down payment on a local purchase therefore ties up more cash than the national example below.
That example uses the January 2026 median U.S. existing-home price, not a Hermosa Beach purchase price. The typical U.S. homebuyer put down 15.2% in December 2025, down from 16.7% a year earlier. These figures offer context, not a required down payment for every buyer.
Before comparing rent with ownership, separate the cash needed at closing from the money you want to keep available afterward. A down payment reduces the amount borrowed, but putting more savings toward it can leave less for moving, repairs, emergencies, or other goals. Renting generally avoids a home-purchase down payment, leaving more cash available, but that flexibility matters only if you plan how to use and protect those funds.
Keeping savings invested doesn’t remove risk. The S&P 500 declined 20% in 2022, illustrating that market investments can lose value. A renter who invests money otherwise used for a down payment could see growth or losses, depending on investment choices and timing. A buyer’s home value can also fluctuate, while mortgage principal payments can build equity over time. Neither path guarantees a better financial result.
Make a like-for-like comparison. Estimate the cash required to buy the home you’re considering, then calculate how much savings you’d retain by renting. Include purchase expenses beyond the down payment, and don’t assume all remaining cash will be invested. Compare investment risk with the possibility of home-value changes, and consider whether you’ll need accessible savings for planned expenses.
| Option | Upfront cash | Investment exposure | Key tradeoff |
|---|---|---|---|
| Buy | Down payment and other purchase costs | Home value can change | Cash committed toward ownership and potential equity |
| Rent | Rental move-in costs | Retained savings may be invested or held | More cash flexibility, with investment risk if invested |
For renting versus buying in Hermosa Beach in 2026, choose by comparing the actual purchase cash requirement with the value you place on keeping savings liquid and managing investment risk.
Homeownership costs, including taxes, insurance, and HOA fees
A mortgage payment is only one part of a Hermosa Beach ownership budget. Compare the loan payment with property taxes, insurance, any HOA fees, and closing expenses before deciding whether a home is affordable.
Mortgage Rates and Monthly Payments
The average 30-year fixed mortgage rate was 6% as of March 5, 2026. A Hermosa Beach payment depends on the purchase price, down payment, loan amount, and rate.
The Los Angeles estimate assumed 20% down, a 30-year fixed loan, and a 6.00% interest rate. A specific home’s price and financing terms drive its estimated payment.
Taxes, Insurance, and HOA Fees
Property taxes and homeowners insurance add recurring expenses beyond principal and interest. HOA fees apply to homes with an association, and the amount depends on that property’s governing documents and services. These costs differ from the mortgage rate: the rate affects borrowing costs, while taxes, insurance coverage, and association fees depend on the home and its circumstances.
Coastal location also makes property-level risk relevant. According to Redfin, 8% of Hermosa Beach properties face severe flooding risk over the next 30 years, affecting 389 properties. Redfin also reports moderate heat risk for 100% of properties over that period. Risk can influence insurance costs and coverage options, so include property-specific exposure in the budget.
To estimate buying costs, compare the home’s price and financing terms, then account for taxes, insurance, any HOA fees, inspections, appraisal, and closing expenses. Closing costs vary with the transaction, loan, and services involved, so include them in the cash needed at purchase rather than focusing only on the down payment. Review the property’s condition and association documents as part of your cost assessment.
For a coastal rental comparison, a Hermosa Beach rental search can help you weigh housing costs without taking on ownership expenses.
Investing savings versus building home equity
The city’s Walk Score is 87 out of 100, and its Bike Score is 71 out of 100; compare actual addresses for beach access and commute convenience.
Buying can build equity as you repay principal, but equity isn’t the same as accessible savings. Changes in home value, your loan balance, and selling costs affect what you keep when you sell. Renting avoids tying a down payment to one property, leaving savings available for other goals. The tradeoff is that rent payments don’t reduce a mortgage balance or build ownership in the home.
Appreciation affects the comparison, but past trends aren’t a forecast for a particular Hermosa Beach property. A traditional rule of thumb has put home appreciation at 4% to 5% annually; the article’s market data describes appreciation at 2% in 2025. Local sale prices can also move differently from long-term assumptions, so don’t build a decision around appreciation alone.
Investing rent-era savings creates a different exposure. The S&P 500 has gained an average of 10% per year over the past 100 years, but that historical average doesn’t remove market volatility. The index declined 20% in 2022. A renter investing savings could experience gains or losses, while a homeowner concentrates more wealth in a single property and local market.
National net-worth figures offer context, not a promise of personal results. Homeowners’ median net worth was $430,000, compared with $10,000 for renters. That difference doesn’t prove homeownership alone caused the gap. Income, savings habits, debt, investment choices, and time all influence household wealth. Compare your full financial position, not one statistic.
Tax treatment can also affect proceeds from a sale. According to the Internal Revenue Service, a homeowner may exclude up to $250,000 in capital gains if single, or up to $500,000 if married filing jointly, subject to the ownership-and-use test. The home must have been owned and used as a primary residence for at least two of the past five years to meet that test.
Use a simple comparison before choosing:
- Estimate how much equity you could build through principal repayment, without assuming a particular resale gain.
- Compare that amount with savings retained by renting and your intended investment approach.
- Account for market fluctuations, selling costs, and any applicable tax exclusion.
- Consider whether beach access, commute patterns, and the specific home justify concentrating savings in that property.
The five-year break-even rule is a traditional guideline, not a universal threshold. Your expected stay, purchase and sale costs, investment alternatives, and the home’s performance all shape the outcome.
Hermosa Beach’s median sale price is a citywide figure, while rents vary by home and location. Walkability and biking score well across the city, but beach access and commute convenience depend on the specific address.
Rental flexibility and maintenance responsibilities
Renting costs include recurring rent and move-in charges specified in the lease. Deposit terms and rent-increase limits depend on the lease and applicable California and local rules. For each Hermosa Beach home, compare the written rent, deposit, fees, notice terms, and renewal conditions.
A lease gives renters a place to live for an agreed term, rather than ownership of a property. That arrangement can suit someone whose work, household needs, or plans may change. For example, if you expect a job change, compare lease end dates with your likely moving plans before choosing a unit. The tradeoff is that moving depends on lease terms and housing availability.
Rent can make housing costs easier to identify. Review the lease for base rent, recurring charges, deposit conditions, and how rent changes are handled. Separate these amounts from optional expenses, such as utilities or parking, when applicable. A clear monthly budget should include every charge the lease assigns to the tenant, not just the advertised rent.
Maintenance responsibilities differ from one rental to another. Read the lease to understand which routine tasks you handle and how to report repairs. A leaking faucet and a failed appliance, for example, may involve different responsibilities depending on the lease and the item. Record the issue, follow the stated reporting process, and keep written communication about repair requests.
Owners face a different set of decisions. They must budget for upkeep and repairs, while renters generally rely on the lease and owner responsibilities for covered property issues. Homeowners can choose when to make improvements, but they also pay for the work and manage its timing. Renters trade that control for fewer direct decisions about a building’s long-term maintenance.
Compare flexibility by looking beyond the lease term. A renter may find it easier to relocate when a term ends, but moving still involves logistics, deposits, and finding another suitable rental. A buyer has more control over the home, but moving means selling or keeping the property. In Hermosa Beach, consider beach access, commute needs, and whether those priorities may change.
Use this practical review before signing a rental agreement:
- Identify the lease term, renewal process, and notice requirements.
- List rent, deposit, and every lease-defined recurring charge.
- Read how rent increases are addressed under applicable rules.
- Clarify repair-reporting steps and which maintenance tasks the lease assigns.
- Compare the lease end date with your likely work and household plans.
For a household prioritizing flexibility, a coastal rental search can help compare Hermosa Beach homes against preferred lease terms, location, and daily routines.
How duration of stay affects the rent-or-buy decision
Your expected stay affects how much time you have to offset buying and selling costs. A five-year stay, a ten-year stay, and a fifteen-year stay create different comparisons: rent remains an expense, while ownership can build equity. No timeline alone makes buying cheaper. Home price, financing, rent, upkeep, and the eventual sale all affect the result.
For a five-year comparison, add up rent across the lease periods and compare it with the full cost of owning and selling. Include purchase expenses, mortgage payments, taxes, insurance, maintenance, and selling costs. Then account for the loan balance repaid and the home’s value when you leave. The traditional five-year break-even rule is a starting point, not a guaranteed result. Transaction costs and property performance determine whether ownership catches up.
Over ten years, ownership has more time for principal repayment to build equity, while rent and any increases continue. Compare actual out-of-pocket costs for both options, then include the savings a renter retains and how those funds are used. A buyer should also model a sale at the end of the period: equity is realized through a sale or other financing, not simply by living in the home.
Over fifteen years, ownership has more time for principal repayment and changes in home value to affect equity. It also means more years of responsibility for repairs, insurance, taxes, and other property costs. Renters retain flexibility, but continue paying rent throughout each lease. Use the same housing needs and investment assumptions for both options.
Build a side-by-side estimate for each horizon:
- Five years: weigh the short ownership period against purchase and resale expenses.
- Ten years: track rent changes, principal repaid, upkeep, and retained savings.
- Fifteen years: include longer-term maintenance and the home’s estimated sale proceeds.
- All three: compare the same home type, household needs, and expected move date.
Hermosa Beach’s market conditions also affect planning. Homes spent a median of 46 days on the market in September 2026, so a future sale requires time and coordination. That figure describes the market period, not a guaranteed selling timeline for an individual property. Include the work of preparing, listing, and completing a sale in your moving plan.
Choose the horizon that matches your credible plans, then test a shorter and longer stay. If a job change or household shift could move your date, compare the financial effect of leaving earlier. Plan a Hermosa Beach home search around your expected timeline and ownership priorities.
Robert Neff, Ph.D., Realtor®: Buyer Search & Negotiation Services
If your comparison points toward ownership, Robert Neff, Ph.D., Realtor® offers buyer search and negotiation services. He can help align your search with your budget, preferred location, and practical priorities, then support negotiations when you find a suitable property in Hermosa Beach or elsewhere along the South Bay coast.
If your plans or timeline point toward renting, Robert Neff offers coastal rental search to help you compare local options. For a relocation or first purchase, relocation and first-time buyer guidance provides step-by-step assistance. The right next move depends on whether your numbers and plans favor renting, buying, or preparing to sell.
For a thoughtful discussion of your Hermosa Beach housing plans, contact Robert Neff, Ph.D., Realtor®.
Choose the next step that fits your plans
The right housing decision should support more than today’s budget. Consider how your plans may change, what kind of home suits your daily life, and whether you want the responsibilities of ownership. For renting vs. buying in Hermosa Beach in 2026, a clear next step is to turn your preferred timeline and priorities into a focused housing plan.
If you’re ready to explore ownership, Robert Neff, Ph.D., Realtor® offers buyer search and negotiation services. Relocation and first-time buyer guidance can help structure a move or first purchase. If your plans shift toward selling, Robert also offers residential property listing and marketing. Each path starts with the decision you’re preparing to make.
Bring your questions about location, timing, and the kind of move you’re considering. A conversation can help you clarify the next step without forcing a choice before you’re ready. Contact Robert Neff, Ph.D., Realtor® to discuss your Hermosa Beach housing plans and move forward with greater clarity.
Frequently Asked Questions
Is it cheaper to rent or buy?
Renting had the lower estimated monthly payment in a January 2026 Los Angeles metro comparison. That mortgage estimate assumed 20% down and a 6.00% rate, and excluded taxes, insurance, and other ownership costs. It’s metro-level context, not a direct comparison for a specific Hermosa Beach home.
Opportunity cost: What else could the money do?
Money used for a down payment could instead remain available for emergencies, other goals, or investments. Consider how much you’d actually invest, your time horizon, and how you’d respond to losses. The S&P 500 gained an average of 10% per year over the past 100 years, but declined 20% in 2022. Those figures illustrate volatility, not a forecast or a guaranteed alternative to home equity.
What is the housing market like in Hermosa Beach today?
Hermosa Beach home sales were active in September 2026: 54 homes sold, up 12.1% year over year. Homes spent a median of 46 days on the market, while the sale-to-list price ratio was 99.1%. These citywide measures describe recent transactions, not the likely price or selling time for a particular property. Home condition, location, and buyer demand shape each listing’s outcome.
What is the median rent for apartments and houses in Hermosa Beach in 2026?
A useful rental comparison separates apartments from houses because size, condition, location, and included features differ. Lease terms and proximity to the beach can also affect rent. Compare homes with similar layouts and locations, then include recurring charges and utilities where applicable. A single figure can hide meaningful differences, especially when comparing a compact apartment with a detached home.
What are home prices and recent sale trends in Hermosa Beach in 2026?
The median was down 2.8% year over year for the three months ending September. In September, 17.0% of homes sold above list price, while 24.6% had price drops. These measures show varied negotiating outcomes: review comparable properties and their recent sale histories when assessing a home.
What are property taxes, insurance, HOA fees, and maintenance costs in Hermosa Beach?
These expenses depend on the specific property, its assessed value, insurance coverage, association rules, and condition. Before buying, review the property’s tax information, insurance terms, HOA documents if applicable, and inspection findings. A home with aging systems, for example, may call for a different maintenance budget than a recently updated one. Add each recurring or likely expense to the mortgage estimate to understand the broader ownership budget.
What are Hermosa Beach home inventory, rental availability, and vacancy trends in 2026?
For homes, September 2026 activity included 54 sales and a median 46 days on market. Those figures describe completed sales and marketing time, not the total number of homes available. Rental availability and vacancy can shift as leases begin or end, so compare current listings that fit your needs. Track suitable options by property type, location, lease timing, and terms rather than relying on sales data as a rental measure.
How do Hermosa Beach neighborhoods differ in home prices, rents, commute, and beach access?
Home prices and rents vary by home and location, while beach access and commute convenience depend on the specific address. Hermosa Beach has a citywide Walk Score of 87 and Bike Score of 71, but compare individual addresses for neighborhood-level differences.


